Asian Markets Slide as Chip Sell-Off, Rising Oil and Earnings Anxiety Trigger Risk-Off Tuesday

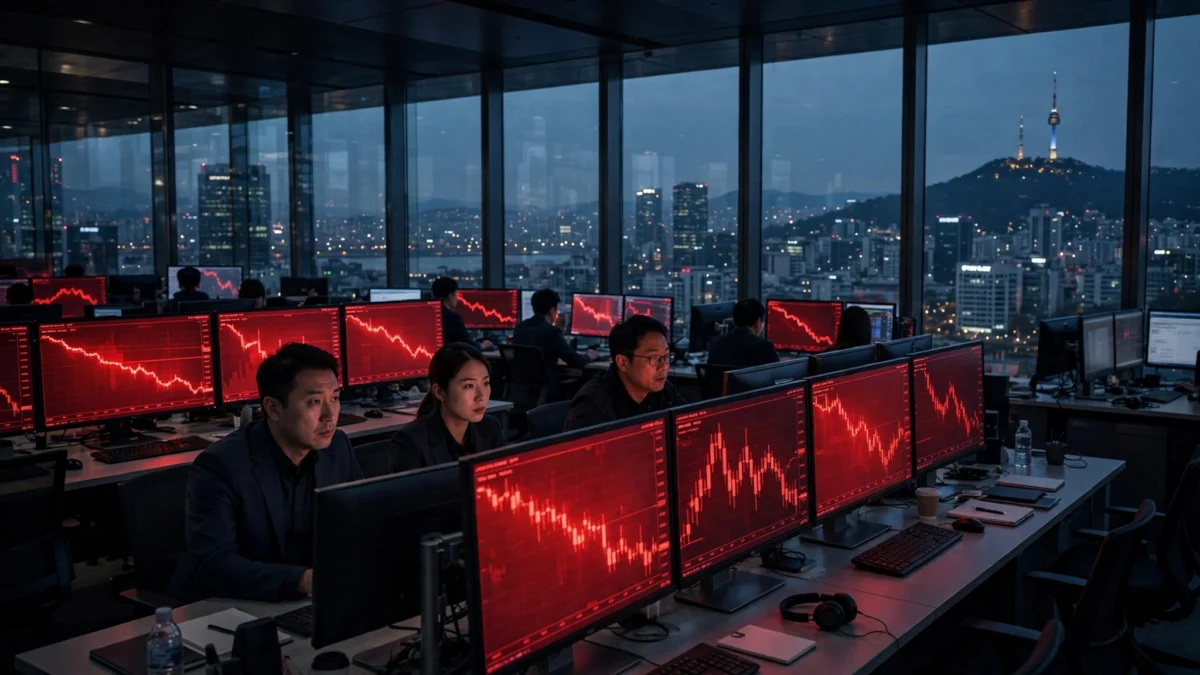
Asian equity markets fell sharply on Tuesday, with technology shares leading the decline as investors pulled back from risk ahead of a packed week of corporate earnings and inflation data, while oil prices climbed toward two-week highs and geopolitical tensions kept energy markets on edge.
According to Reuters, MSCI’s broadest index of Asia-Pacific shares outside Japan dropped 2 per cent in early trading on Tuesday, October 13. South Korea’s technology-heavy KOSPI index tumbled as much as 6 per cent in early dealing, and Japan’s Nikkei 225 sank 2.6 per cent after markets there returned from a holiday. The sell-off followed an overnight decline on Wall Street, where the tech-heavy Nasdaq composite fell 0.5 per cent, dragged down by semiconductor stocks.
The cautious mood extended to currencies. The United States dollar held near an 18-month high, the euro traded at $1.1157, and the Japanese yen stood at 158.50 per dollar, according to the Reuters report.
Tuesday’s retreat marked another bruising session for the region’s chipmakers, which have borne the brunt of mounting doubts about the durability of the artificial-intelligence rally. According to Bloomberg reporting carried by Market Index, Samsung Electronics and SK Hynix — the twin heavyweights of the Korean market — each fell more than 7 per cent, putting both on track for a fifth consecutive losing session. The KOSPI was down as much as 6.2 per cent at one point, trading below its 200-day moving average and sitting roughly a third beneath its June record.
Foreign investors have been dumping Korean shares at a remarkable pace: Bloomberg data showed they had sold more than US$6 billion worth of KOSPI-listed shares in October alone, even as Samsung posted record earnings last week — results that failed to lift the stock.
According to Korean business outlet KED Global, which cited Yonhap reporting, South Korean stocks plunged on Tuesday morning as foreign selling extended a spree in Samsung and SK Hynix, rattled by signs of faster technological progress at Chinese memory-chip makers. One name in particular is rattling nerves: China’s CXMT, which plans a higher-density server memory product by the end of 2026, reviving long-standing fears that Chinese competition will compress margins for the established Korean giants.
The unease was compounded by an unusually blunt warning from one of the industry’s most powerful figures. Broadcom chief executive Hock Tan said many AI investors “have no clue what they are investing in,” adding that financing the AI buildout may prove a bigger problem than any shortage of chips, according to Bloomberg reporting carried by Market Index.
Oil climbs as geopolitical risk returns to centre stage
While technology stocks fell, energy prices moved the other way. According to Reuters, Brent crude futures traded at $105.90 per barrel on Tuesday, near a two-week high, as investors weighed geopolitical developments across the Middle East and the Russia-Ukraine theatre.
Oil markets have been volatile in recent weeks, according to the same report, as investors contend with supply risks from attacks on Saudi Arabia — including strikes that have affected operations around Riyadh’s airport — while also weighing the prospect of additional diesel supplies from Russia, following a controversial US-Russia diesel arrangement that has drawn bipartisan criticism in Washington.
The twin forces of rising crude and a fragile energy ceasefire are feeding directly into inflation anxiety. “Markets are rediscovering that geopolitics matters most when it feeds back into inflation,” Charu Chanana, chief investment strategist at Saxo in Singapore, told Reuters. “The renewed jump in oil is keeping pressure on yields and taking some shine off expensive growth stocks, especially as the Russia-Ukraine energy truce looks fragile and Middle East supply risks remain live.”
That dynamic — geopolitics feeding inflation feeding bond yields feeding valuation pressure — is precisely what has put expensive technology stocks in the firing line.
Wall Street’s chip wobble bleeds into Asia
The Asian sell-off did not begin in Asia. “A lot of it has to do with the chip selloff we saw on Wall Street overnight. That’s bleeding into the Asian region,” Kyle Rodda, a senior analyst at Capital.com, told Reuters. “When you add another jump in oil prices and some positioning ahead of inflation data and earnings, you have all the ingredients for a risk-off day in Asia,” he said.
The concern, analysts say, is not simply that chips have risen a lot — it is that the AI trade now has to clear two hurdles at once. First, the technological question: can non-Chinese chipmakers hold their lead as companies like CXMT climb the memory ladder? Second, the financial question: can the enormous capital spending behind AI data centres be sustained when money costs more and the revenue streams remain, for many investors, speculative?
Hock Tan’s remark cuts to that second question. If financing, not chip supply, is the binding constraint on the AI boom, then high interest rates — kept aloft by oil-driven inflation — are not a side-show but the main event.
A gauntlet of data and earnings lies ahead
Investors are also bracing for a relentless calendar. According to Morningstar’s weekly market preview, Tuesday brings earnings from JPMorgan, Wells Fargo and Citigroup — alongside healthcare giants UnitedHealth Group and Johnson & Johnson — with Bank of America and BlackRock to follow on Wednesday.
The week’s economic releases matter just as much. The United States Consumer Price Index for September arrives on Wednesday, October 14, followed by the Producer Price Index on Thursday. According to Morningstar’s preview, the CPI report is expected to show monthly inflation of 0.6 per cent, up from 0.4 per cent in August, with year-over-year CPI at 3.6 per cent. The Federal Reserve’s Beige Book is also due Wednesday, and Thursday brings initial unemployment claims and retail sales data.
In Australia, sentiment is already souring. According to National Australia Bank’s monthly survey, carried by Market Index, business confidence fell four points to minus 13 in September — a third consecutive monthly decline that puts it in the bottom 5 per cent of readings in the survey’s history. Business conditions held at minus 1, seven points below the long-run average, while the employment index slid three points to its lowest level in five years, signalling that labour demand may slow from here.
Analysis: Why It Matters
Tuesday’s sell-off is significant not because any single market fell — Asian equities fall every other week — but because of the unusual alignment of forces behind it. Three separate risk channels, which usually offset one another, are pointing in the same direction.
The first channel is the AI valuation question. For two years, the dominant market narrative held that the constraint on artificial intelligence was physical: not enough chips, not enough power, not enough data-centre capacity. That narrative made every supply bottleneck good news for chipmakers. Hock Tan’s intervention flips the frame. If the binding constraint is now financial — the sheer cost of funding the buildout at prevailing interest rates — then the same high yields that protect lenders’ margins punish borrowers’ valuations. A KOSPI that is a third below its June high, with foreign investors pulling out more than $6 billion in two weeks, is a market voting that the financing question is real.
The second channel is the geopolitics-to-inflation pipeline. Attacks on Saudi infrastructure, an 18-month-high dollar, and a fragile Russia-Ukraine energy arrangement have pushed crude back toward two-week highs. Energy is one of the few inputs that cannot be hedged away by clever financial engineering: it flows into transport, manufacturing and household budgets alike, which is why central bankers watch it so closely. Chanana’s observation — that geopolitics matters most when it feeds back into inflation — is the mechanism by which a strike near Riyadh becomes a repricing of Samsung’s shares in Seoul. Investors are not pricing the conflict itself; they are pricing the interest rates that the conflict’s inflationary fallout forces central banks to maintain.
The third channel is timing. Tuesday’s decline arrived at the start of the earnings season that, in Reuters’ words, “will set the tone for the rest of the year.” Bank earnings are the economy’s early warning system: loan books, deal pipelines and credit losses reveal what households and businesses are actually experiencing, long before official statistics catch up. Add Wednesday’s CPI print to the mix, and the market is staring down two binary events in 48 hours — each capable of moving yields, each moving in the same direction as the others if the news is bad.
For the average observer, the lesson is less about any index level and more about correlation. When technology valuations, energy prices and rate expectations all move on the same geopolitical news flow, diversification within equities offers less protection than textbooks suggest. The dollar’s strength near 18-month highs reflects exactly this: money is moving toward the one asset that benefits from all three channels at once.
There is also a specifically Asian dimension worth watching. Korea’s market is now the clearest laboratory for the AI debate: two dominant memory-chip producers, rising Chinese competition, and a heavy reliance on foreign portfolio flows. The activation of the Korea Exchange’s “sidecar” trading curb — a five-minute halt on programme sell orders triggered by plunging KOSPI 200 futures, reportedly the 22nd such halt this year, according to FXStreet — shows a market structure under genuine stress, not just a routine pullback. Whether Seoul stabilises after earnings from the US banks or spirals further will be read globally as a verdict on the whole AI trade.
What to Watch Next
- Wednesday’s US CPI report (October 14) — the single most important data point of the week. A hotter-than-expected 0.6 per cent monthly print would harden expectations that rates stay high, likely deepening the pressure on growth stocks. A cooler reading could spark a sharp relief rally.
- Tuesday’s bank earnings — JPMorgan, Wells Fargo and Citigroup report on the same day as the sell-off. Commentary on credit quality, loan demand and deal pipelines will show whether the real economy is holding up behind the market volatility.
- Thursday’s PPI and retail sales — producer prices and consumer spending will complete the week’s inflation-and-demand picture, alongside weekly jobless claims.
- The won, the yen and the dollar — with the dollar near 18-month highs, Asian central banks are in a bind: intervene to defend currencies, or let weakness feed import-price inflation. Any sign of coordinated concern would move markets fast.
- Chinese chip momentum — any further detail on CXMT’s roadmap, or on export-control responses from Washington, could re-rate the entire memory sector. Watch Samsung’s and SK Hynix’s next guidance for how seriously they take the threat.
Sources
- Reuters: Asian stocks dive as focus on earnings, geopolitics — market moves, oil prices, dollar, analyst quotes
- KED Global: Foreign selling slams Kospi as China chip fears hit Samsung, SK Hynix — KOSPI morning plunge, foreign selling, CXMT
- Market Index (Bloomberg): ASX 200 live — NAB business confidence, Kospi slump, Hock Tan comments — confidence survey, foreign outflows, Broadcom CEO remarks
- Morningstar: What’s Happening in the Markets This Week — earnings calendar and economic release schedule

About the Author — Abdul Mannan
Related Articles
Bull Market Turns Four as Wall Street Opens a High-Stakes Week of Bank Earnings, CPI and Oil Jitters
The S&P 500 bull market turned four on Monday, nearly 120 per cent above its October 2022 low,…
Central Banks Enter 2027 on a Tighter Path as IMF Urges “Prudently Hawkish” Stance on Rates
Bloomberg Economics expects central banks across 90 per cent of the world economy to head into 2027 with…
Wall Street Braces for a Blockbuster Q3 Earnings Season as Big Banks Kick Off Tuesday With Profits Seen Jumping 30%
Analysts expect S&P 500 profits to jump nearly 30% as JPMorgan, Wells Fargo, Citigroup and Goldman Sachs report…