Borrowed Silicon: Who Will Pay When the AI Dream Starts Billing?

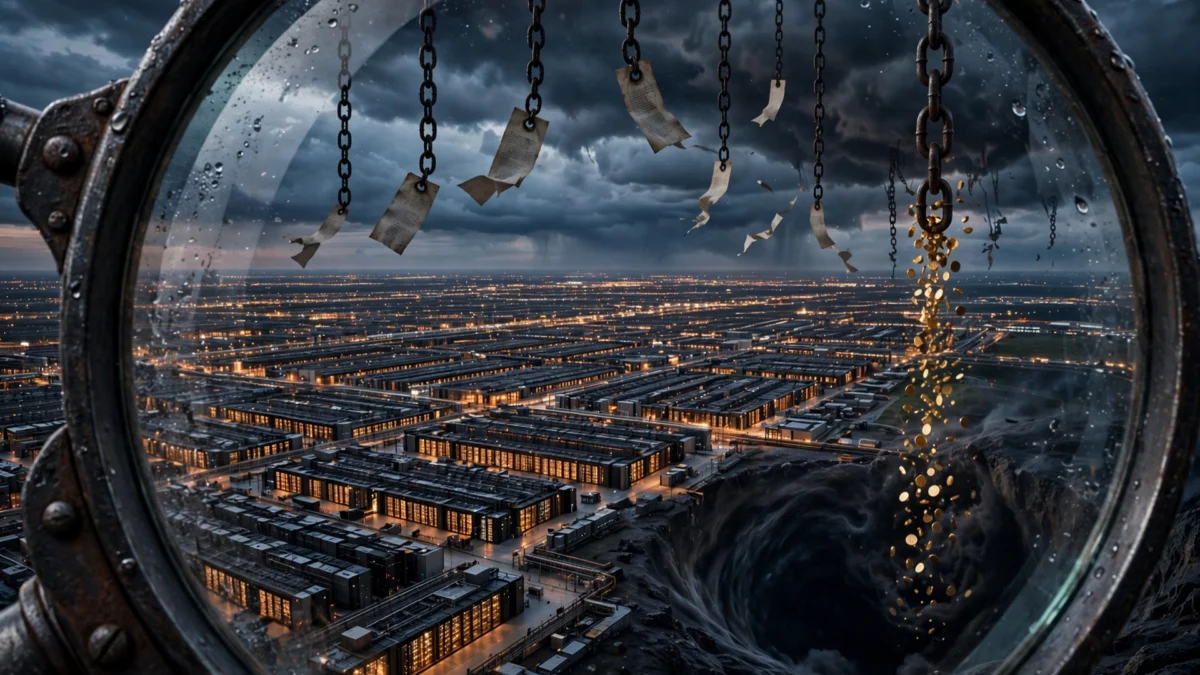
What if the cleverest machines ever built are being bought with the silliest money?
That is the question I cannot shake this week, as the financial wires carried a story so brazen it reads like satire. SpaceX — Elon Musk’s rocket company, which is still burning cash faster than it earns it — is in talks to raise $40 billion in debt so it can buy artificial-intelligence chips from Nvidia. The Financial Times broke the story on 6 October; Reuters confirmed the shape of it. Roughly $10 billion in bank loans, another $30 billion in investment-grade bonds, led by Apollo Global Management, with the giant bond house Pimco reportedly among the lenders in talks.
Stop for a moment and let that number sit. Forty billion dollars. Borrowed. Not to build a factory, not to launch a fleet — but to buy somebody else’s product, which will sit in data centres humming away in the hope that, someday, the revenues arrive to pay the interest. The deal is expected to close in 2027.
The Loop That Feeds on Itself
And here is where the story turns from large to strange. Nvidia is not merely the seller in this arrangement. Filings show the chipmaker owns just under 123 million SpaceX shares, worth close to $21 billion at the end of June. SpaceX, for its part, has committed to building its AI infrastructure exclusively on Nvidia’s chips. And Nvidia — the company receiving the money — is itself helping assemble the financing pools that lend its customers the cash to pay it.
Follow the money, as Nigel Green, the chief executive of deVere Group, put it this week, and it comes straight back to where it started. The supplier bankrolls the buyer; the buyer buys the supplier’s goods; every dollar in the loop gets counted as growth somewhere. Strip out the circular flows, and the true level of independent demand becomes very hard to measure.
Green’s warning deserves to be quoted in full: “The AI build out started on cash. It’s increasingly running on credit, and credit changes the risk profile entirely. Debt has to be repaid on schedule, whether the revenues show up or not. And this debt is landing in the bond funds and pension pots of savers right around the world.”
Read that last line again, reader. The bond funds and pension pots of savers right around the world. That means you. That means me. The retirement savings of schoolteachers and shopkeepers are being quietly converted into IOUs on chips whose value depends on a future nobody has seen.
Not a One-Off: $1.5 Trillion of Appetite
This is not a one-off. The Wall Street Journal reported this week that Broadcom is looking for $50 billion in financing, and that Oracle is out raising money for AI chips too. Morgan Stanley estimates that AI infrastructure will need $1.5 trillion in outside financing by 2028. Amazon, according to the Financial Times, is seeking to move about $8 billion of Nvidia chips into an outside investment vehicle and lease them back, just to keep the hardware off its own balance sheet. Meanwhile JPMorgan, as reported by Bloomberg, counts $65 billion of deeply distressed US leveraged loans — the highest since the pandemic, with software-sector stress driving the surge.
Now, I will say this in fairness: the demand is real in places. Samsung projected a 783 per cent jump in third-quarter operating profit — to 107.4 trillion won, about $80 billion — on the back of this very hunger for chips and memory. The furnace is genuinely hot. My question is not whether artificial intelligence matters. My question is who pays for the furnace, and what happens to them if the fire cools.
History’s Mirror: Railways, Nortel and 2008
And this is where history steps onto the stage, because history has watched this exact play before — different costumes, same script.
In the 1840s, Britain was seized by the railway mania. Fortunes were borrowed, bonds were sold, and ordinary savers poured their money into railway schemes that existed only on paper. The “Railway King”, George Hudson, was worshipped as a genius of finance — until the crash of 1847 exposed the rot, and thousands of small investors were ruined. The railways themselves were real; the country did get its iron roads. But the men and women who paid for the dream with borrowed money were left holding the wreckage.
A century and a half later, the telecommunications giant Nortel ran a subtler version of the same trick. At the height of the dot-com boom, Nortel extended lavish vendor financing to its own customers — lending them the money to buy Nortel’s equipment, then booking the sales as growth. When the bubble burst and the customers could not pay, the “growth” evaporated, and one of the great companies of the age collapsed into the history books. I remember that story well, because it taught the financial world a lesson it seems determined to unlearn: when a supplier guarantees the loans its customers use to buy its products, everything rests on the collateral holding its value. If the next generation of hardware makes today’s chips obsolete faster than expected — as Green warned this week — the collateral, the earnings and the equity stakes all lose value at the same time.
And then there was 2008, when the world’s banks discovered that the mortgage-backed securities sitting in every pension fund on Earth were backed by loans that would never be repaid. The paper said “investment grade”. The reality said otherwise. Nobody, in the end, could explain what the collateral was actually worth. Sound familiar? Today’s lenders, banking sources told Reuters on 1 October, already doubt that chips can serve as long-term collateral — and want Nvidia itself to guarantee the deals. The collateral is so exotic that the market will not touch it without the seller’s own signature.
Cathedrals Built on Borrowed Gold
I do not write this to mock the engineers. The chips are marvels; the data centres rising across deserts and plains are cathedrals of human ingenuity. But cathedrals were also financed, and the financiers of the Middle Ages knew something Wall Street keeps forgetting: a cathedral built on borrowed gold still belongs, in the end, to the lender.
Consider the arithmetic that nobody in the AI trade wants to recite. SpaceX lost $4.28 billion in the first quarter of this year on revenue of $4.69 billion — it is spending nearly twice what it earns, and now proposes to add $40 billion of debt on top. The debt must be serviced in dollars, on schedule, whether the orbital AI constellation it is meant to power — a million satellites, not one of which has yet launched — ever earns a cent. Meanwhile the 10-year US Treasury yield has touched a 24-year high of 5.326 per cent, and minutes from the Federal Reserve’s last meeting show most members consider another rate hike likely by year end. Money, in other words, has never been more expensive — and the AI industry has never borrowed more of it.
This is the oldest story in commerce, and it always ends the same way. The boom begins with cash and vision. Then comes the clever money — the leverage, the circular deals, the special-purpose vehicles, the collateral nobody can quite value. The music plays, everyone dances, and the bill is passed quietly to the people who were never invited to the party: the savers, the pensioners, the small bond funds holding what their managers swore was safe.
So I ask you, reader, the question the column always ends on: when the machines finally start thinking, whose money will they be thinking with — and who will be left holding the receipt?
The railway investors of 1847 thought they were buying the future. They were right. They just never asked who would pay for it.
Sources & References
- Reuters — “Asia shares subdued, bonds swamped by AI debt wave”, 8 October 2026.
- Financial Times, via Tech Times — SpaceX’s $40bn Apollo-led debt talks for Nvidia chips, reported 6 October 2026.
- IFA Magazine — deVere Group CEO Nigel Green on the “dangerous loop”, 7 October 2026.
- AI Stock Wire — lenders demanding bigger Nvidia guarantees on chip-backed loans; Amazon’s $8bn chip SPV; Morgan Stanley’s $1.5tn estimate.
- Bloomberg, via Archynetys — JPMorgan: US deeply distressed leveraged loans at $65bn, highest since the pandemic.

About the Author — Abdul Mannan
Related Articles
Fed Minutes Reveal Deep Split Over September Rate Hike as Most Officials Signal Another Move This Year
Minutes of the Federal Reserve's September meeting show a unanimous vote to raise rates was paired with deep…
Wall Street Drops as 10-Year Treasury Yield Hits Highest Since 2002, With Fed Minutes in Focus
US stocks fell on Wednesday as the 10-year Treasury yield touched its highest level since 2002, with Brent…
S&P 500 Closes at First Record Since August as AI Rally Broadens — but 5.3% Bond Yields Flash a Warning
The S&P 500 and Nasdaq closed at records on Tuesday as the AI trade broadened into power stocks…