Schneider Electric Agrees $22.6 Billion Deal to Buy US Software Firm PTC

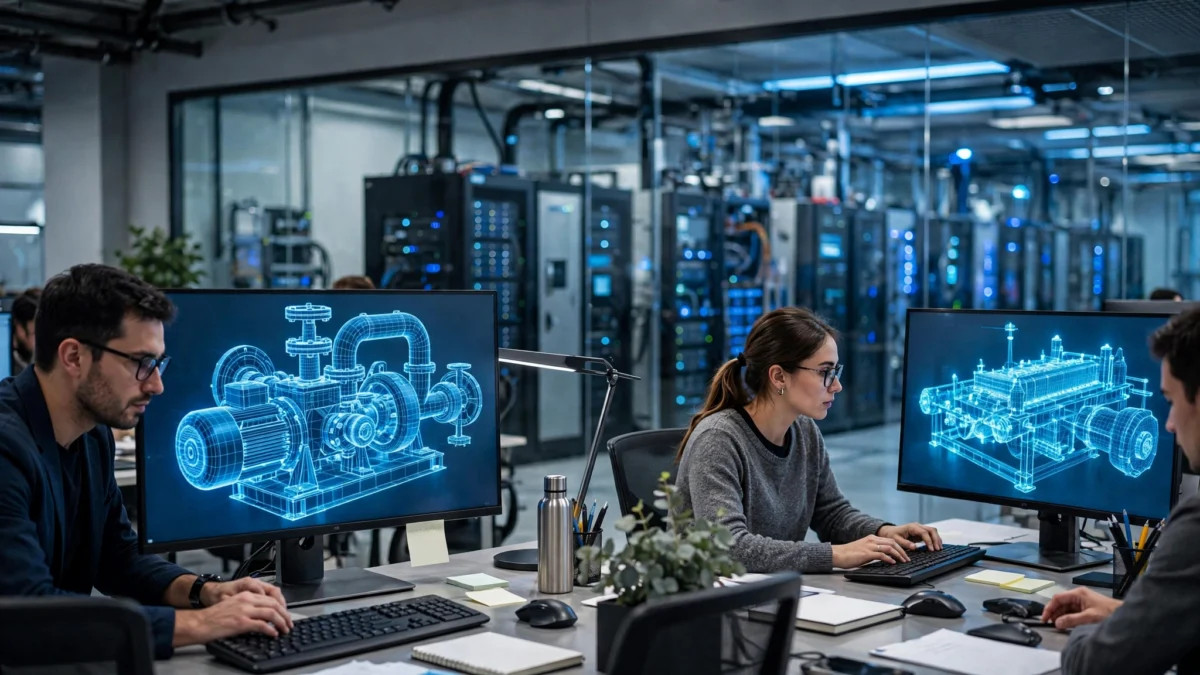
France’s Schneider Electric said on Monday it had agreed to buy the United States industrial software company PTC in an all-cash deal valuing the Boston-based firm’s equity at around $22.6 billion, marking a decisive step in the French engineering group’s transformation into a software-driven company.
The $205-per-share cash offer represents a 42.3 per cent premium to PTC’s last closing price, implying an enterprise value of $23.7 billion, according to Reuters. PTC’s board has recommended that shareholders approve the deal, the Wall Street Journal reported. Schneider said the transaction would be financed through a combination of equity and new debt issuance and is expected to close in the third quarter of 2027.
Investors gave the announcement a mixed reception. Shares in Schneider fell more than 8 per cent in European morning trading, while PTC’s stock jumped 35 per cent in US premarket exchanges to about $195.60, according to Barron’s.
The acquisition deepens Schneider’s push into software. PTC provides software for designing, manufacturing and servicing products across multiple sectors and has benefited from growing demand for its AI-powered tools, according to Reuters. Schneider said the deal aims to create one of the largest industrial-software portfolios at a time when the rise of artificial intelligence is reshaping customer needs. After the deal, nearly a quarter of Schneider’s revenue would come from software and services, up from less than a fifth currently, the Wall Street Journal reported.
The move continues a buying spree. In June, Schneider agreed to buy Cognite, an industrial data and AI software provider, adding to its existing AVEVA industrial-software business. It also reflects how far Schneider has come from its roots in industrial-revolution France: once known mainly for industrial components such as fuses and circuit breakers, it now builds the backbone of data centres, supplying cooling units, server racks and critical power distribution equipment. The booming demand for data centres, particularly in the United States, is driving Schneider’s earnings and helping offset weakness in some traditional electrical-equipment markets; in July the company lifted its annual revenue forecast after reporting record first-half results.
Why It Matters
Schneider is paying a heavy premium — more than 42 per cent — because industrial software has become one of the most contested assets in corporate Europe. The company’s logic is straightforward: its fortunes are increasingly tied to the data-centre build-out and the AI boom, and owning the software that designs and runs industrial systems gives it a full stack, from the physical equipment to the digital layer that controls it. In an age of “industrial AI”, as Schneider describes it, technology moves beyond digital applications and becomes embedded in machines and physical products — and Schneider wants to own that layer.
But the market’s cold response to its own shares tells the other half of the story. Investors are not questioning the strategy so much as the price and the execution risk: Schneider must now finance and integrate three software assets — PTC, AVEVA and Cognite — while carrying the debt of a $22.6 billion deal that will not close for nearly two years. As IG analyst Angeline Ong told Barron’s, the strategy makes sense, but investors are asking whether Schneider can finance and integrate all three assets, and that execution risk is what is driving the shares lower.
The deal is also a signal about the broader software market. After a volatile year in which fears of AI disruption hit software stocks, a $22.6 billion all-cash bid at a 42 per cent premium suggests that corporate buyers see value — and a long runway — in industrial software. What to watch now: regulatory clearances on both sides of the Atlantic, the PTC shareholder vote, and whether Schneider can deliver on the promised synergies — about €250 million in annual cost savings by the third year after completion and roughly €800 million in revenue synergies. If it succeeds, Schneider becomes the industry’s leading “software and AI powerhouse”; if it stumbles under the debt and integration load, today’s premium will look expensive.
Sources

About the Author — Abdul Mannan
Related Articles
Asian Stocks Rally as Weak US Jobs Data Cools Fed Rate-Hike Bets
Asian stocks rose on Monday as a weak US September jobs report slashed bets on an October Fed…
Ken Griffin’s Record $3B Carnegie Mellon Gift ‘a Loss for New York,’ Business Leaders Say
New York business leaders call Ken Griffin's record $3 billion Carnegie Mellon donation "a loss" for the city…
OPEC+ Holds November Oil Output Steady as Middle East Security Risks Persist
OPEC and its allies agreed on Sunday to keep November oil production targets unchanged, as elevated Middle East…